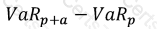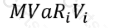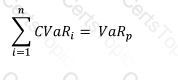

Halloween Sale Special - 75% Discount Offer - Ends in 0d 00h 00m 00s - Coupon code: big75certs

8008 Exam Dumps : PRM Certification - Exam III: Risk Management Frameworks, Operational Risk, Credit Risk, Counterparty Risk, Market Risk, ALM, FTP - 2015 Edition

PDF
8008 pdf
 Real Exam Questions and Answer
 Last Update: Oct 20, 2026
 Question and Answers: 362 With Explanation
 Compatible with all Devices
 Printable Format
 100% Pass Guaranteed
$21.25  $84.99
8008 exam
PDF + Testing Engine
8008 PDF + engine
 Both PDF & Practice Software
 Last Update: Oct 20, 2026
 Question and Answers: 362
 Discount Offer
 Download Free Demo
 24/7 Customer Support
$33.75  $134.99
Testing Engine
8008 Engine
 Desktop Based Application
 Last Update: Oct 20, 2026
 Question and Answers: 362
 Create Multiple Test Sets
 Questions Regularly Updated
  90 Days Free Updates
  Windows and Mac Compatible
$25  $99.99
Last Week Results
32 Customers Passed PRMIA
8008 Exam
Average Score In Real Exam
86.7%
Questions came word for word from this dump
88.6%
PRMIA Bundle Exams
PRMIA Bundle Exams
 Duration: 3 to 12 Months
 2 Certifications
  16 Exams
 PRMIA Updated Exams
 Most authenticate information
 Prepare within Days
 Time-Saving Study Content
 90 to 365 days Free Update
$208*
Free 8008 Exam Dumps

Verified By IT Certified Experts

CertsTopics.com Certified Safe Files

Up-To-Date Exam Study Material

99.5% High Success Pass Rate

100% Accurate Answers

Instant Downloads

Exam Questions And Answers PDF

Try Demo Before You Buy

Certification Exams with Helpful Questions And Answers

PRM Certification - Exam III: Risk Management Frameworks, Operational Risk, Credit Risk, Counterparty Risk, Market Risk, ALM, FTP - 2015 Edition Questions and Answers

Question 1

Which of the following are measures of liquidity risk

I. Liquidity Coverage Ratio

II. Net Stable Funding Ratio

III. Book Value to Share Price

IV. Earnings Per Share

Options:

A.

III and IV

B.

I and II

C.

II and III

D.

I and IV

Buy Now
Question 2

Which of the formulae below describes incremental VaR where a new position 'm' is added to the portfolio? (where p is the portfolio, and V_i is the value of the i-th asset in the portfolio. All other notation and symbols have their usual meaning.)

A)

B)

C)

D)

Options:

A.

Option A

B.

Option B

C.

Option C

D.

Option D

Question 3

Which of the following credit risk models relies upon the analysis of credit rating migrations to assess credit risk?

Options:

A.

KMV's EDF based approach

B.

The CreditMetrics approach

C.

The actuarial approach

D.

The contingent claims approach