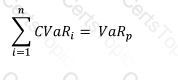Power Up Your Study Prep: Black Friday 75% Discount! Use coupon code below to save! - Ends in 0d 00h 00m 00s - Coupon code: big75certs

PRMIA 8008 Exam With Confidence Using Practice Dumps

Exam Code:
8008
Exam Name:
PRM Certification - Exam III: Risk Management Frameworks, Operational Risk, Credit Risk, Counterparty Risk, Market Risk, ALM, FTP - 2015 Edition
Certification:
Vendor:
Questions:
362
Last Updated:
Nov 13, 2026
Exam Status:
Stable
PRMIA 8008

8008: PRM Certification Exam 2025 Study Guide Pdf and Test Engine

Are you worried about passing the PRMIA 8008 (PRM Certification - Exam III: Risk Management Frameworks, Operational Risk, Credit Risk, Counterparty Risk, Market Risk, ALM, FTP - 2015 Edition) exam? Download the most recent PRMIA 8008 braindumps with answers that are 100% real. After downloading the PRMIA 8008 exam dumps training , you can receive 99 days of free updates, making this website one of the best options to save additional money. In order to help you prepare for the PRMIA 8008 exam questions and verified answers by IT certified experts, CertsTopics has put together a complete collection of dumps questions and answers. To help you prepare and pass the PRMIA 8008 exam on your first attempt, we have compiled actual exam questions and their answers. 

Our (PRM Certification - Exam III: Risk Management Frameworks, Operational Risk, Credit Risk, Counterparty Risk, Market Risk, ALM, FTP - 2015 Edition) Study Materials are designed to meet the needs of thousands of candidates globally. A free sample of the CompTIA 8008 test is available at CertsTopics. Before purchasing it, you can also see the PRMIA 8008 practice exam demo.
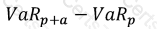
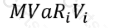
PRM Certification - Exam III: Risk Management Frameworks, Operational Risk, Credit Risk, Counterparty Risk, Market Risk, ALM, FTP - 2015 Edition Questions and Answers

Question 1

Which of the formulae below describes incremental VaR where a new position 'm' is added to the portfolio? (where p is the portfolio, and V_i is the value of the i-th asset in the portfolio. All other notation and symbols have their usual meaning.)

A)

B)

C)

D)

Options:

A.

Option A

B.

Option B

C.

Option C

D.

Option D

Buy Now
Question 2

If the systematic VaR for an equity portfolio is $100 and the specific VaR is $80, then which of the following is true in relation to the total VaR:

Options:

A.

Total VaR is greater than $180

B.

Total VaR is $20

C.

Total VaR is $180

D.

Total VaR is less than $180

Question 3

Which of the following statements is true in relation to a normal mixture distribution:

I. Normal mixtures represent one possible solution to the problem of volatility clustering

II. A normal mixture VaR will always be greater than that under the assumption of normally distributed returns

III. Normal mixtures can be applied to situations where a number of different market scenarios with different probabilities can be expected

Options:

A.

II and III

B.

III

C.

I and II

D.

I, II and III