
Power Up Your Study Prep: Black Friday 75% Discount! Use coupon code below to save! - Ends in 0d 00h 00m 00s - Coupon code: big75certs

PRMIA 8010 Exam With Confidence Using Practice Dumps

Exam Code:
8010
Exam Name:
Operational Risk Manager (ORM) Exam
Certification:
Vendor:
Questions:
240
Last Updated:
Nov 9, 2026
Exam Status:
Stable
PRMIA 8010

8010: PRM Certification Exam 2025 Study Guide Pdf and Test Engine

Are you worried about passing the PRMIA 8010 (Operational Risk Manager (ORM) Exam) exam? Download the most recent PRMIA 8010 braindumps with answers that are 100% real. After downloading the PRMIA 8010 exam dumps training , you can receive 99 days of free updates, making this website one of the best options to save additional money. In order to help you prepare for the PRMIA 8010 exam questions and verified answers by IT certified experts, CertsTopics has put together a complete collection of dumps questions and answers. To help you prepare and pass the PRMIA 8010 exam on your first attempt, we have compiled actual exam questions and their answers. 

Our (Operational Risk Manager (ORM) Exam) Study Materials are designed to meet the needs of thousands of candidates globally. A free sample of the CompTIA 8010 test is available at CertsTopics. Before purchasing it, you can also see the PRMIA 8010 practice exam demo.

Operational Risk Manager (ORM) Exam Questions and Answers

Question 1

Under the standardized approach to determining operational risk capital, operations risk capital is equal to:

Options:

A.

a fixed percentage of the latest gross income of the bank

B.

a varying percentage, determined by the national regulator, of the gross revenue of each of the bank's business lines

C.

15% of the average gross income (considering only the positive years) of the past three years

D.

a fixed percentage (different for each business line) of the gross income of the eight specified business lines, averaged over three years

Buy Now
Question 2

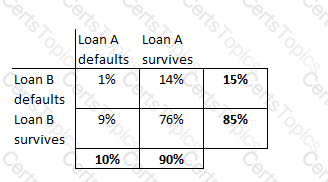
A portfolio has two loans, A and B, each worth $1m. The probability of default of loan A is 10% and that of loan B is 15%. Theprobability of both loans defaulting together is 1%. Calculate the expected loss on the portfolio.

Options:

A.

500000

B.

250000

C.

1000000

D.

240000

Question 3

Which of the following credit risk models considers debt as including a put option on the firm's assets toassess credit risk?

Options:

A.

The actuarial approach

B.

The CreditMetrics approach

C.

The contingent claims approach

D.

CreditPortfolio View