

PRMIA Related Exams
Last Week Results
32 Customers Passed PRMIA
8006 Exam
8006 Exam
Average Score In Real Exam
Questions came word for word from this dump

PRMIA Bundle Exams
Duration: 3 to 12 Months
2 Certifications
16 Exams
PRMIA Updated Exams
Most authenticate information
Prepare within Days
Time-Saving Study Content
90 to 365 days Free Update
$208*

 103.11.e1 is the standard deviation of the asset to be hedged, and
 103.11.e2 is the standard deviation the asset being used to hedge against price movements in x, then the minimum variance hedge ratio is given by the expression
 103.11.e3. In this question, correlation = 0.00378/(6%*7%) = 0.9. The minimum variance hedge ratio is given by (6%/7%)*0.9 = 0.77
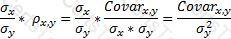 103.11.a3


